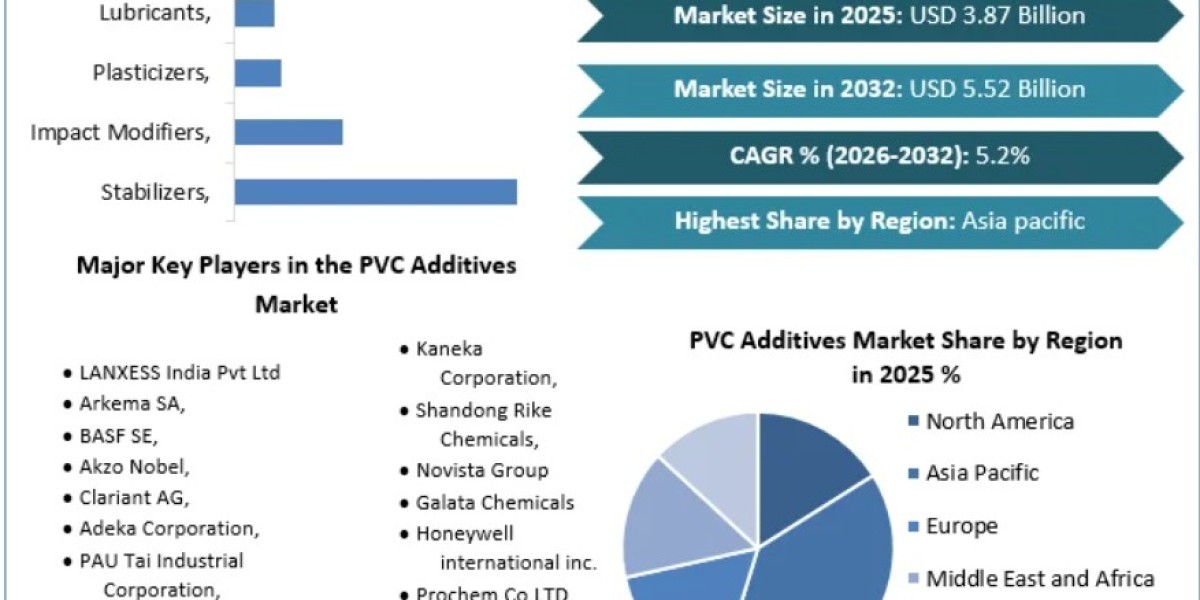

The global PVC Additives Market, valued at USD 6.8 billion in 2024, is on a strong upward trajectory, projected to expand at a steady compound annual growth rate (CAGR) of 6.0% through 2030 to reach nearly USD 9.6 billion, according to a comprehensive market intelligence report published by Stellar Market Research. The market's accelerated momentum is driven by an intensive industry-wide shift toward high-performance, eco-friendly formulations, rigorous regulatory compliance regarding toxic emissions, and surging investments in urban infrastructure and green building construction across developing economies.
The global PVC additives landscape is experiencing a paradigm shift from traditional commodity formulations to high-efficiency, sustainable chemical solutions. Historically reliant on basic heat stabilizers and standard plasticizers, the industry is navigating tightening global environmental mandates—such as restrictions on heavy metal stabilizers and hazardous plasticizers—that demand next-generation alternatives.
Key Findings from the Report
Market Valuation & Horizon: The global PVC Additives Market is valued at USD 6.8 billion in 2024 and is projected to scale up to USD 9.6 billion by 2030, registering a 6.0% CAGR during the forecast period.
Leading Product Segment: Heat and light Stabilizers dominate the product landscape, commanding a market revenue share of over 33.7%, driven by their essential role in preventing thermal degradation during high-temperature extrusion and injection molding processes.
Dominant End-Use Application: Building and Construction remains the premier application sector, holding a market share exceeding 38.4%, anchored by continuous global demand for PVC pipes, window profiles, flooring, and cable insulation.
Regional Dominance: Asia Pacific leads the global marketplace, capturing a dominant revenue share of 43.8% in 2024, fueled by large-scale infrastructure projects, rapid housing expansion, and heavy industrial output in China and India.
Fastest-Growing Region: Latin America and the Middle East & Africa are emerging as high-potential growth pockets, driven by rising investments in water management infrastructure and commercial real estate development.
Technology Shift: Accelerated adoption of eco-friendly, non-toxic calcium-zinc (Ca-Zn) stabilizers and bio-based plasticizers to meet stringent regional environmental regulations.
Investment Relevance: Heightened focus on strategic mergers, acquisitions, and capacity expansions by leading chemical enterprises targeting specialized, high-margin additive portfolios.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/PVC-Additives-Market/2471
Market Drivers and Restraints
Drivers
Booming Infrastructure and Construction Spending: Ongoing global investments in smart cities, modern water distribution networks, and affordable housing initiatives heavily rely on durable PVC piping and profiles, directly scaling additive consumption.
Stringent Environmental Regulations: Tightening international compliance standards prohibiting toxic heavy-metal stabilizers (such as lead-based systems) compel compounders to transition toward advanced, eco-friendly alternatives.
Technological Advancements in Polymer Science: Innovations in multifunctional additives—such as anti-scratch modifiers, low-volatility plasticizers, and UV-resistant stabilizers—extend the lifespan of finished goods in harsh climatic environments.
Restraints
Raw Material Price Volatility: Fluctuations in petrochemical feedstock and intermediate chemical prices create profit margin pressures for Tier-2 and Tier-3 additive manufacturers.
Strict Environmental and Disposal Compliance: High regulatory hurdles and rigorous testing protocols for new chemical formulations can prolong product approval timelines and increase research overhead.
Technology, Regulation, and Sustainability Trends
The structural transformation of the PVC additives industry is heavily anchored in sustainability and circular economy mandates. Environmental agencies across Europe and North America have systematically phased out conventional hazardous additives, steering formulators toward circular-compatible additives that do not impede mechanical recycling streams. Concurrently, chemical leaders are adopting biomass-certified raw materials to lower carbon footprints. On the operational front, manufacturers are integrating advanced process automation and AI-driven quality control systems to optimize chemical dispersion, reduce batch failure rates, and achieve precise compliance with zero-emission manufacturing goals.
Regional Insights
Asia Pacific: Cementing its leadership position, Asia Pacific benefits from massive domestic demand in China and India. Government-backed infrastructure modernization, aggressive urban development, and expanding automotive manufacturing hubs continue to absorb high volumes of thermal stabilizers and impact modifiers.
Europe: Characterized by mature regulatory frameworks, Europe leads in the adoption of sustainable, bio-based, and lead-free PVC stabilizer systems. Strict REACH regulations and ambitious green building certifications dictate regional purchasing behavior, pushing compounders toward premium eco-additives.
North America: Supported by a robust construction and automotive retrofit cycle, the U.S. and Canadian markets emphasize high-performance additives that withstand extreme weather variations and meet stringent building safety codes.
Recent Industry Developments
BASF SE (2023): Launched the industry’s first biomass balance offerings for plastic additives, successfully replacing fossil-based feedstocks with certified renewable raw materials to support circular supply chains.
Clariant AG (2022): Introduced specialized anti-scratch additives at K 2022 designed for polyolefin and engineered PVC formulations, significantly boosting the reusability and lifecycle durability of automotive and consumer goods plastics.
Songwon Industrial Co., Ltd. (2024): Expanded its specialty chemical manufacturing output to support rising global demand for advanced polymer stabilizers tailored for extreme weather construction applications.
Kaneka Corporation (2025): Scaled up production capacity for high-performance impact modifiers, providing enhanced impact resistance and weatherability for exterior building profiles.
Arkema SA (2025): Completed a strategic portfolio optimization to strengthen its footprint in sustainable, bio-sourced functional additives aimed at reducing greenhouse gas emissions across the polymer value chain.
Competitive Landscape
The global PVC additives market features a consolidated yet fiercely competitive ecosystem comprising major chemical multinationals alongside agile regional specialists. Prominent market leaders—including BASF SE, Dow Inc., Arkema SA, Clariant AG, Songwon Industrial Co., Ltd., Kaneka Corporation, Solvay, LyondellBasell, Formosa Plastics Corporation, and INEOS—focus heavily on research and development, strategic partnerships, and facility expansions. Competitive differentiation increasingly relies on proprietary formulations that deliver superior thermal stability, regulatory compliance, and customized technical support to downstream compounders.
Analyst Commentary
"The PVC additives market is no longer driven solely by cost efficiency; it is undergoing a profound structural evolution anchored in sustainability, regulatory alignment, and functional premiumization," said a Senior Research Analyst at Stellar Market Research. "Formulators who successfully transition away from legacy chemistries to advanced, circular-compatible stabilizers and bio-based modifiers will capture disproportionate value as global infrastructure and green building standards become more rigorous over the remainder of the decade."
Future Outlook
Through 2030, the global PVC additives market is poised for steady, quality-driven expansion. Demand will increasingly favor high-performance, multifunctional, and eco-compliant formulations over conventional volume-based products. As emerging economies accelerate smart infrastructure projects and developed regions enforce stricter zero-carbon building codes, investments in green chemistry and advanced extrusion technologies will surge. Companies that integrate sustainability into their core R&D pipelines while expanding specialized regional supply chains will be best positioned to capture long-term market leadership.
For further information, click the following link:https://www.stellarmr.com/report/req_sample/PVC-Additives-Market/2471
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656