Advanced IC Substrates Market Overview
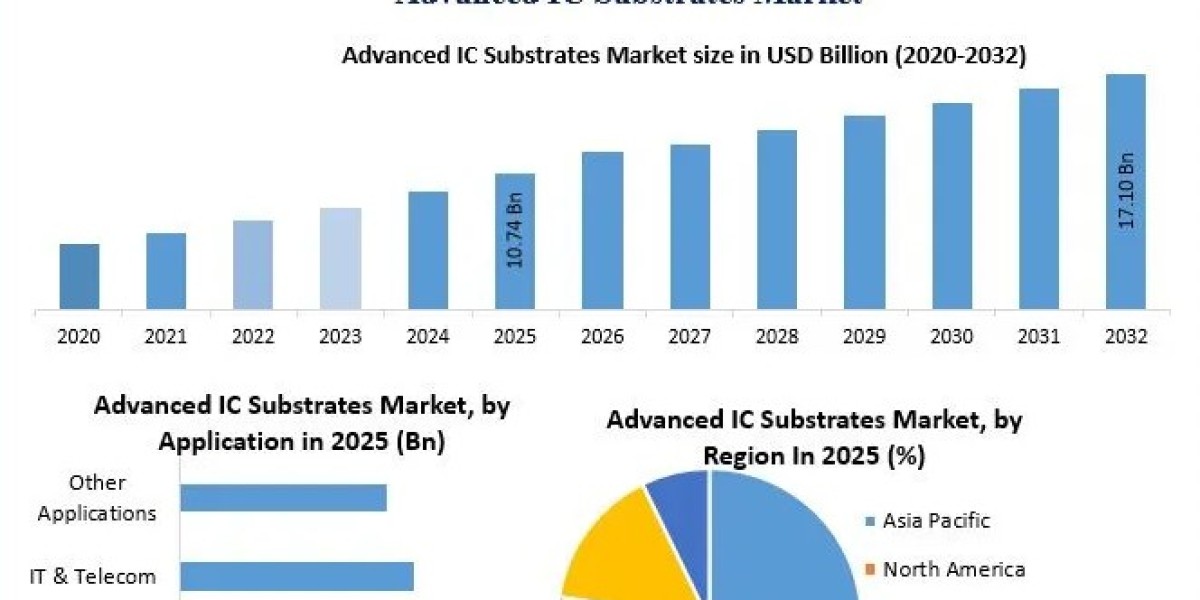
The global Advanced IC Substrates Market was valued at USD 10.74 billion in 2025 and is projected to reach nearly USD 17.09 billion by 2032, registering a compound annual growth rate (CAGR) of 6.85% during the forecast period from 2026 to 2032. The market is experiencing steady growth due to the increasing demand for high-performance semiconductor packaging, miniaturized electronic components, advanced computing systems, and next-generation communication technologies. The growing adoption of artificial intelligence (AI), high-performance computing (HPC), 5G connectivity, the Internet of Things (IoT), and automotive electronics is further strengthening demand for advanced integrated circuit (IC) substrates worldwide.
Dive deeper into market insights, trends, segmentation, and competitive landscape here: https://www.maximizemarketresearch.com/request-sample/145825/
Advanced IC substrates are essential components in semiconductor packaging, providing electrical connections between semiconductor chips and printed circuit boards. These substrates support signal transmission, power distribution, thermal management, and mechanical stability while enabling the integration of increasingly complex semiconductor devices into compact electronic systems. As semiconductor manufacturers continue to develop smaller, faster, and more energy-efficient chips, advanced IC substrates are becoming increasingly important to the electronics manufacturing ecosystem.
The expansion of consumer electronics, smartphones, gaming consoles, wearable devices, automotive electronics, and data center infrastructure is creating new opportunities for manufacturers. Increasing demand for sophisticated packaging technologies, including flip-chip ball grid array (FC-BGA) and flip-chip chip-scale package (FC-CSP), is encouraging industry participants to invest in research and development, production capacity, and advanced substrate materials.
Asia-Pacific remains a major manufacturing and consumption center because of its established semiconductor ecosystem, electronics production capabilities, and investments in advanced packaging. Countries such as China, Taiwan, South Korea, and Japan play important roles in the global supply chain, while increasing semiconductor investments in North America and Europe are creating additional opportunities for technology suppliers.
According to the market assessment, the Advanced IC Substrates Market is expected to maintain a positive growth trajectory through 2032. However, manufacturers must address challenges associated with capital-intensive production, manufacturing complexity, material costs, and the growing technical requirements of next-generation semiconductor packaging.
Advanced IC Substrates Market Growth and Research Methodology
The growth of the Advanced IC Substrates Market is closely associated with the increasing complexity of semiconductor devices and the transition toward advanced packaging architectures. The demand for higher interconnection density, improved electrical performance, efficient heat dissipation, and smaller package dimensions is encouraging semiconductor companies to adopt advanced substrate technologies.
Dive deeper into market insights, trends, segmentation, and competitive landscape here: https://www.maximizemarketresearch.com/request-sample/145825/
The market report evaluates historical developments, current industry conditions, emerging technological trends, and future growth opportunities. It examines market size, revenue forecasts, competitive positioning, and demand across major application areas and geographic regions.
The research also considers the competitive landscape, including established substrate manufacturers, semiconductor packaging companies, material suppliers, and emerging technology participants. Strategic developments, manufacturing investments, product innovations, and regional expansion initiatives are assessed to provide stakeholders with an understanding of the market's future direction.
The report incorporates market segmentation and competitive assessment, alongside analytical frameworks such as PORTER's Five Forces and PESTEL analysis, to evaluate competitive pressures, regulatory conditions, technological developments, and macroeconomic influences that may affect market growth.
Advanced IC Substrates Market Drivers and Trends
Increasing Demand for High-Performance Computing and Artificial Intelligence
The growing adoption of artificial intelligence, machine learning, cloud computing, and data-intensive applications is one of the major factors supporting the Advanced IC Substrates Market. AI accelerators, graphics processing units (GPUs), application-specific integrated circuits (ASICs), and high-performance processors require advanced packaging solutions capable of supporting high-speed signal transmission, increased input/output density, and efficient power delivery.
FC-BGA substrates are particularly relevant to high-performance processors and computing systems because they can accommodate complex interconnections and demanding electrical requirements. As data center operators expand infrastructure to support generative AI, cloud services, and large-scale computing workloads, demand for advanced semiconductor packaging is expected to increase.
The transition toward more sophisticated chip architectures is also encouraging manufacturers to explore next-generation substrate materials and packaging technologies. Glass-core substrates, improved organic materials, and finer circuit structures are attracting industry attention because they may provide enhanced dimensional stability and support higher interconnection density.
Growing Adoption of 5G and Next-Generation Communication Technologies
The expansion of 5G networks and the increasing use of connected devices are contributing to market growth. Advanced IC substrates support semiconductor components used in communication infrastructure, smartphones, networking equipment, and wireless systems.
The deployment of 5G base stations and the development of high-frequency communication components require substrates that can deliver reliable electrical performance and support compact package designs. In addition, the growing demand for faster data transmission and lower latency is increasing the importance of advanced semiconductor packaging in telecom infrastructure.
As telecommunications companies continue upgrading their networks and consumers adopt increasingly sophisticated mobile devices, FC-CSP and FC-BGA technologies are expected to benefit from rising demand across relevant applications.
Miniaturization of Consumer Electronics and Wearable Devices
The continuous development of smaller and more capable electronic products is another important growth driver. Smartphones, smartwatches, fitness trackers, wireless accessories, gaming consoles, and portable computing devices increasingly integrate multiple functions into limited physical space.
Advanced IC substrates enable compact packaging while maintaining the electrical connectivity required for sophisticated semiconductor components. The increasing integration of processors, memory, connectivity chips, and power-management components is encouraging manufacturers to adopt substrate solutions with higher routing density and improved performance.
The consumer electronics segment is also benefiting from growing demand for high-resolution displays, advanced imaging, mobile gaming, and energy-efficient computing. These trends are expected to sustain demand for advanced packaging technologies throughout the forecast period.
Expansion of Automotive Electronics and Electric Vehicles
The automotive industry is becoming an increasingly important application area for advanced IC substrates. Modern vehicles incorporate semiconductor components for advanced driver-assistance systems (ADAS), infotainment, battery management, power electronics, connectivity, and vehicle control.
Electric vehicles and hybrid vehicles require reliable electronic systems capable of operating under demanding thermal and electrical conditions. Advanced substrates support the integration of automotive semiconductor components and can contribute to improved package reliability and system performance.
The development of connected vehicles, autonomous driving technologies, and intelligent transportation systems is expected to increase semiconductor content in vehicles. Consequently, automotive electronics represents a potential source of long-term demand for advanced substrate manufacturers.
Technological Advancements and Manufacturing Capacity Expansion
Continuous investment in research and development is transforming the advanced substrate industry. Manufacturers are working to improve circuit-line precision, substrate flatness, layer integration, manufacturing yields, and material performance to meet increasingly demanding semiconductor packaging requirements.
Companies are also investing in production facilities and process improvements to address demand from AI computing, networking, and advanced processors. At the same time, collaborations between substrate producers, semiconductor manufacturers, equipment suppliers, and material developers are helping accelerate the commercialization of next-generation technologies.
Nevertheless, advanced substrate manufacturing remains capital-intensive. Equipment costs, process complexity, and stringent quality requirements can affect production economics and create barriers to entry for smaller manufacturers.
Advanced IC Substrates Market: Key Market Segments Covered
The Advanced IC Substrates Market is segmented by type, application, and region. These categories help identify major demand sources and opportunities across semiconductor packaging and end-use industries.
By Type
The market is segmented into FC-BGA and FC-CSP.
FC-BGA (Flip-Chip Ball Grid Array): FC-BGA is an important substrate technology used in high-performance processors, networking equipment, graphics processors, and computing systems. Its ability to support complex interconnections, high routing density, and demanding electrical requirements makes it suitable for applications requiring substantial processing power and high data throughput. Increasing investments in AI infrastructure, data centers, and high-performance computing are expected to support demand for FC-BGA substrates.
FC-CSP (Flip-Chip Chip-Scale Package): FC-CSP substrates are designed for compact semiconductor packages where space efficiency, electrical performance, and integration are important. They are widely relevant to mobile and consumer electronics, including smartphones, wearable devices, and other portable products. The continuing miniaturization of electronic components and increasing integration of semiconductor functions are expected to support this segment.
By Application
The market is segmented into Mobile & Consumer, Automotive & Transportation, IT & Telecom, and Other Applications.
Mobile & Consumer: This segment benefits from demand for smartphones, tablets, wearable devices, gaming systems, and other consumer electronics. Increasing processor capabilities, wireless connectivity, and product miniaturization are supporting the adoption of advanced IC substrates.
Automotive & Transportation: Advanced driver-assistance systems, electric vehicles, connected-car technologies, and electronic control systems are creating opportunities for advanced semiconductor packaging. The need for reliability and efficient thermal management is particularly important in automotive applications.
IT & Telecom: This segment includes data centers, servers, high-performance computing systems, networking equipment, and telecommunications infrastructure. Demand for AI accelerators, advanced processors, and high-speed communication systems is creating significant opportunities for sophisticated substrate technologies.
Other Applications: This category includes industrial electronics, specialized computing systems, IoT equipment, and other electronic applications requiring reliable semiconductor packaging. Increasing automation and connected industrial systems may contribute to future demand.
By Region
The Advanced IC Substrates Market covers North America, Europe, Asia-Pacific, the Middle East and Africa, and South America.
Asia-Pacific represents a major center for advanced substrate manufacturing and semiconductor packaging, supported by established electronics supply chains and investments in chip production. North America benefits from semiconductor research, AI infrastructure development, and investments in domestic manufacturing capabilities. Europe has opportunities in automotive electronics, industrial applications, and semiconductor technology development. Meanwhile, South America and the Middle East and Africa offer potential opportunities associated with expanding digital infrastructure and electronics adoption.
Regional market performance will depend on semiconductor investment, manufacturing capacity, supply-chain diversification, end-use demand, and government initiatives supporting domestic technology production.
Dive deeper into market insights, trends, segmentation, and competitive landscape here: https://www.maximizemarketresearch.com/request-sample/145825/
Advanced IC Substrates Market: Major Industry Players
The competitive landscape includes established semiconductor substrate manufacturers and electronics technology companies that compete through product development, production capacity, manufacturing efficiency, and strategic partnerships.
Key companies identified in the Advanced IC Substrates Market include:
ASE Group (Taiwan)
TTM Technologies (United States)
KYOCERA Corporation (Japan)
Eastern (United States)
Ibiden (Japan)
AT&S (Austria)
Nan Ya PCB (Taiwan)
Samsung Electro-Mechanics (South Korea)
Fujitsu (Japan)
Daeduck Electronics (South Korea)
Korea Circuit (South Korea)
Shinko Electric Industries (Japan)
Zhen Ding Technology Holding Limited (Taiwan)
Unimicron Technology Corporation (Taiwan)
These companies participate in a competitive environment shaped by semiconductor packaging requirements, customer qualification processes, material innovation, and manufacturing scale. Their strategic priorities include improving substrate performance, increasing production efficiency, expanding advanced packaging capabilities, and developing technologies for next-generation computing and communication applications.
The growing importance of AI processors and high-performance computing is encouraging manufacturers to strengthen their capabilities in high-end substrate production. Partnerships with semiconductor designers, packaging companies, and materials suppliers may also help industry participants respond to evolving customer requirements.
Advanced IC Substrates Market: Recent Industry Developments
Advanced IC substrate manufacturers are increasingly directing investments toward high-end FC-BGA products, next-generation substrate materials, and capacity expansion. Industry activity also reflects the growing need to support AI accelerators, high-performance computing, advanced networking, and increasingly complex semiconductor packages.
Research into glass-core substrates and other advanced materials is gaining attention because of the potential to improve dimensional stability and enable finer interconnection structures. At the same time, established substrate producers are exploring manufacturing improvements and customer diversification to address changing demand patterns and supply-chain constraints.
Capacity investments, research collaborations, and process innovations are expected to remain important competitive strategies during the forecast period. Actual project timelines, investment amounts, and commercialization milestones may vary by company and should be verified against official corporate announcements.
Advanced IC Substrates Market: Regional Insights
Asia-Pacific
Asia-Pacific is a major region in the global Advanced IC Substrates Market due to its strong semiconductor manufacturing ecosystem, extensive electronics production base, and established packaging and testing capabilities. Taiwan, South Korea, Japan, and China are important participants in the regional supply chain.
Taiwan benefits from its advanced semiconductor manufacturing and packaging ecosystem, while South Korea has significant capabilities in memory, electronics, and semiconductor-related technologies. Japan contributes through substrate materials, manufacturing equipment, and advanced electronic components. China continues to invest in semiconductor capabilities and domestic electronics manufacturing.
The region's demand is supported by smartphone production, data center development, 5G deployment, automotive electronics, and industrial automation. Continued investment in advanced packaging and substrate manufacturing is expected to reinforce Asia-Pacific's strategic importance.
North America
North America is benefiting from growing investments in semiconductor manufacturing, AI infrastructure, cloud computing, and advanced processor development. The United States is an important market for high-performance computing and AI accelerators, which require sophisticated packaging technologies.
Government initiatives supporting domestic semiconductor production and supply-chain resilience may create additional opportunities for substrate manufacturers. However, expanding local capacity requires substantial capital expenditure, technical expertise, and long-term customer commitments.
Europe
Europe's market opportunities are closely connected to automotive semiconductor demand, industrial automation, telecommunications, and semiconductor research. Germany, Austria, and other European countries contribute to the region's electronics and semiconductor technology ecosystem.
The transition toward electric vehicles, connected mobility, and energy-efficient industrial systems is expected to support demand for advanced semiconductor packaging. Investments in research and manufacturing capabilities may also strengthen Europe's position in specialized applications.
Middle East and Africa
The Middle East and Africa market is influenced by digital infrastructure development, telecommunications investment, smart-city initiatives, and the gradual expansion of industrial technology adoption. Although advanced substrate manufacturing is less established in many countries across the region, demand for semiconductor-based systems may increase as digital transformation accelerates.
South America
South America's market development is associated with electronics consumption, telecommunications expansion, industrial modernization, and automotive applications. Brazil and Argentina are among the countries contributing to regional demand for electronic products and semiconductor-enabled systems. Growth will depend on investment conditions, technology adoption, and integration with global electronics supply chains.
Frequently Asked Questions (FAQs)
1. What is the projected size of the Advanced IC Substrates Market by 2032?
The Advanced IC Substrates Market is projected to reach nearly USD 17.09 billion by 2032, compared with USD 10.74 billion in 2025.
2. What is the expected CAGR of the Advanced IC Substrates Market during 2026–2032?
The market is expected to grow at a CAGR of 6.85% during the forecast period from 2026 to 2032.
3. What are advanced IC substrates?
Advanced IC substrates are specialized components used in semiconductor packaging to provide electrical connections between integrated circuit chips and printed circuit boards. They support signal transmission, power distribution, mechanical stability, and thermal performance.
4. Which are the major segments of the Advanced IC Substrates Market?
The market is segmented by type into FC-BGA and FC-CSP. By application, it covers Mobile & Consumer, Automotive & Transportation, IT & Telecom, and Other Applications. Regional coverage includes North America, Europe, Asia-Pacific, the Middle East and Africa, and South America.
5. Which type is expected to play an important role in market growth?
FC-BGA is an important segment because of its suitability for high-performance processors, networking equipment, and computing applications that require high routing density and advanced electrical performance. FC-CSP also remains important for compact mobile and consumer electronic devices.
Conclusion
The Advanced IC Substrates Market is positioned for sustained expansion as semiconductor technologies become more complex and demand for high-performance, energy-efficient electronic systems continues to rise. The market's projected growth from USD 10.74 billion in 2025 to nearly USD 17.09 billion by 2032 reflects the increasing importance of advanced packaging in AI computing, telecommunications, automotive electronics, and consumer devices.
Connect With Us:MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.